4 Personal Lines Trends That Increase E&O Exposure
In today’s personal lines environment, operational challenges are not just business hurdles; they can also translate into rising errors & omissions exposure for independent agents.

In today’s personal lines environment, operational challenges are not just business hurdles; they can also translate into rising errors & omissions exposure for independent agents.
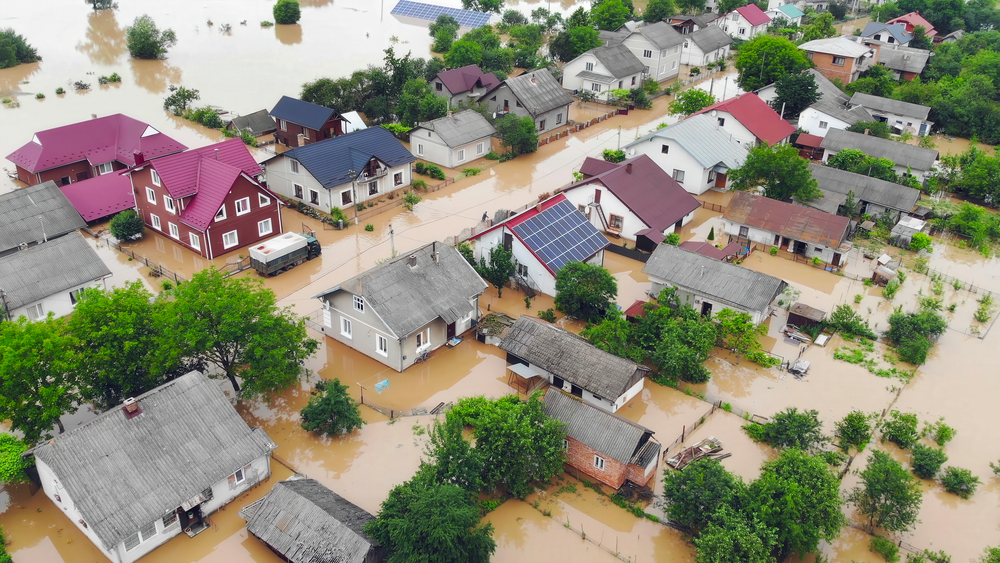
Even routine seasonal changes can create meaningful exposure in non-flood zones, making proactive education and coverage reviews key in the spring months.
The expanded coverage offers employers customizable dental and vision coverage.
As more states legalize cannabis for recreational and medical use, the cannabis industry continues to grow—driving expansion in the insurance market.
As the legal landscape becomes more complex for cannabis clients, insurers are treating that complexity as real exposure. Here’s how agents can help.
Supplemental benefits can go a long way to reducing client churn and ensuring that the clients who do stay are happy.
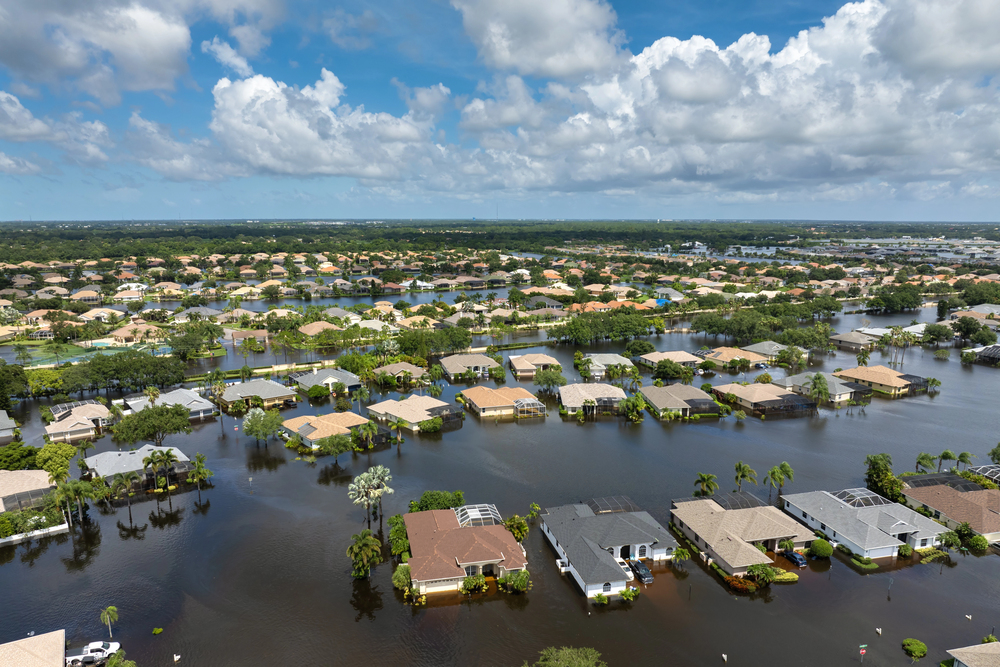
Rainfall-driven flooding, overwhelmed stormwater systems and runoff from new development are increasingly common drivers of loss. Those realities do not always align neatly with boundary flood zones.
The policy protects the tools, equipment and livelihood of small specialty contractors who focus on service, repair and standard installation work.
By tailoring flood coverage to a client’s actual risk and financial exposure, agents ensure they have the protection they need without the unnecessary costs.
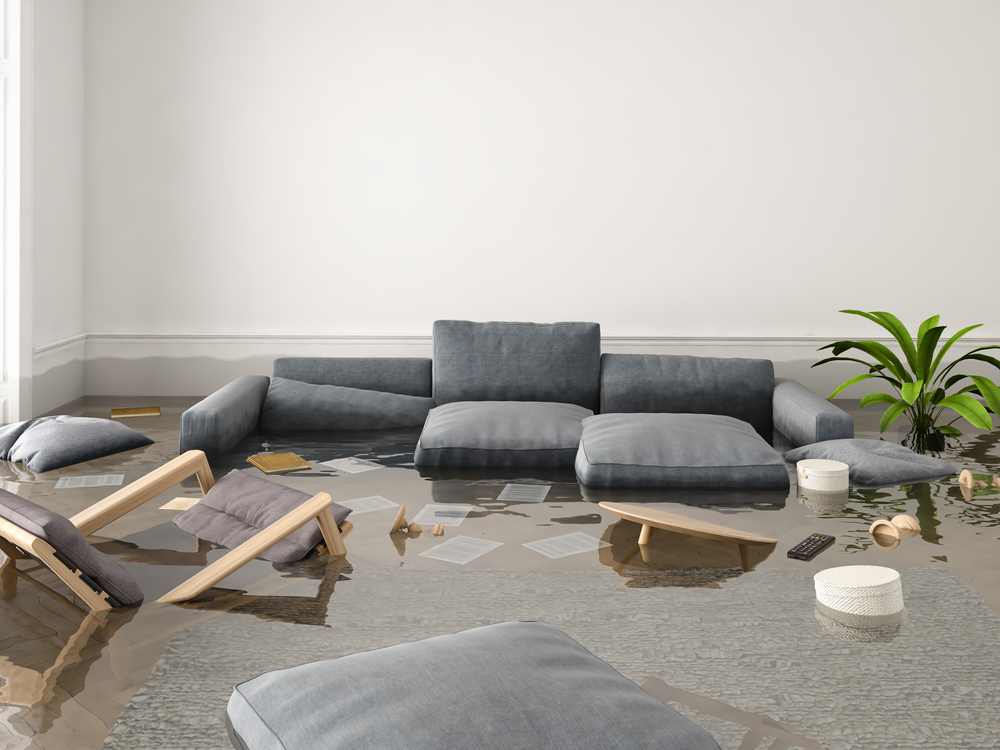
As flood risk becomes more complex and less tied to traditional flood maps, agents play a key role in helping customers understand their real exposure.