4 Strategies for Agents to Enhance Customer Value in the Current Market
How independent agents can add value through comprehensive consultation and risk mitigation.

How independent agents can add value through comprehensive consultation and risk mitigation.
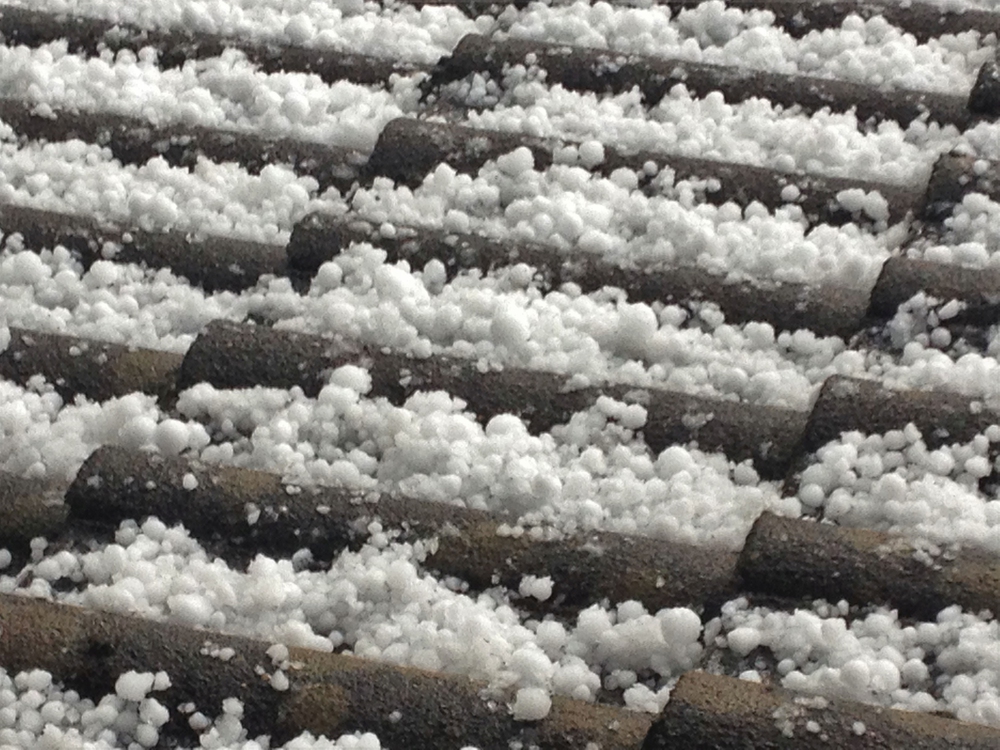
To keep premiums affordable, homeowners carriers are excluding coverage for what used to be standard covered perils. Cosmetic hail damage is one of those coverages that is increasingly becoming excluded.
Jewelry may be the quintessential Valentine’s Day gift, but it has also become the darling of would-be fraudsters.
The fire chief is a volunteer, and while volunteer activity is included in the policy, the agent believes that the position would still be excluded as a professional service.

Sometimes, policies with this endorsement are the only ones available to clients, including those with high-value historic homes. What is an appropriate disclaimer to explain this?
For agents and brokers serving high-net worth clients, 2025 will be about more than just managing policies—the evolving market demands adaptability and a forward-looking perspective.
How do you explain how a wind or hail buyback policy works? And is a deductible applied to these types of policies?
2025 is set to be a year of significant change with shifting markets and evolving weather patterns, making it more important than ever to ensure your homeowner clients are adequately protected.

While sky-high premiums prompted half of U.S. auto insurance customers to shop for a new plan last year, few alternatives meant most stayed put. That’s all about to change.
“More personalized coverage will be key future trends in the industry,” says independent agent Jon Ross. “We are also seeing a shift to the customer taking on more of the risk with higher deductibles or endorsements to buy coverage at set limits.”
