Petting Zoo Insurance: Does a Host Need Coverage for Animals It Doesn’t Own?
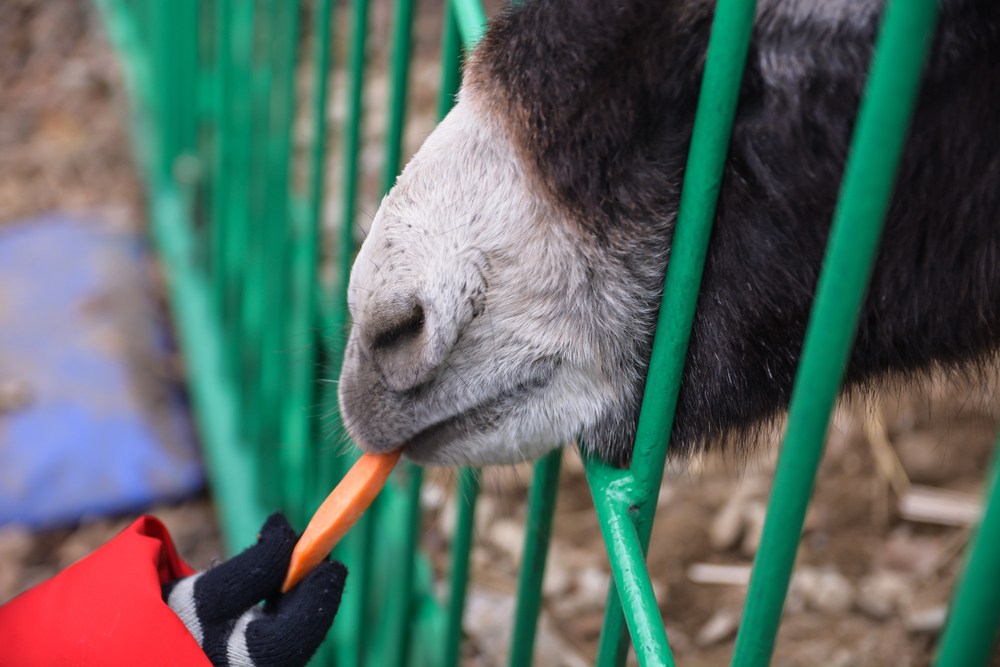
Q: A local chamber of commerce will be hosting an event where there will be a petting zoo. A person who owns some animals is letting the chamber use them for the zoo. The chamber is willing to obtain its own petting zoo insurance policy, but what coverages would it need since it doesn’t own the animals? Event attendees will be required to sign a waiver.
Response 1: Unless the chamber’s commercial general liability insurance policy excludes coverage for liability from bodily injury or property damage arising out of the presence of animals on the premises, any loss should be covered. However, I would suggest that the chamber ask the animal owner to name the chamber as an additional insured on the owner’s liability insurance policy. That will reduce the chance that the chamber’s own policy will become involved.

What Are Your Goals for 2027?
Response 2: Unfortunately, I have more questions than answers. How is the chamber involved? Is the event being held on its property? Is there a written agreement between any of the parties?
Did the chamber prepare the waiver? Is it realistic that every participant will sign the waiver? I believe most attorneys will tell you most waivers are not enforceable, especially when it comes to minors.
Response 3: Both the chamber and animal owner should have insurance, as it is unlikely that either entity will have the proper protection for both of the two parties. The chamber should notify its CGL underwriter to obtain coverage for the special event—or if that is not available, it should acquire a special events policy in its name.
The entity providing the petting zoo should also have insurance in place for its activities, which might include a business auto policy for transporting animals and CGL for setting up the petting zoo and managing the event.
What Do the Experts Think?

Ideally, that entity would have a contract with the chamber that requires it to defend, indemnify and hold the chamber harmless for its activities. The contract should include insurance requisites with additional insured status for the chamber. That way, the animal owner would provide primary insurance for the event, with the chamber’s policies to be excess.
This question was originally submitted by an agent through the Big “I” Virtual University’s (VU) Ask an Expert service, with responses curated from multiple VU faculty members. Answers to other coverage questions are available on the VU website. If you need help accessing the website, request login information.
This article is intended for general informational purposes only, and any opinions expressed are solely those of the author(s). The article is provided “as is” with no warranties or representations of any kind, and any liability is disclaimed that is in any way connected to reliance on or use of the information contained therein. The article is not intended to constitute and should not be considered legal or other professional advice, nor shall it serve as a substitute for obtaining such advice. If specific expert advice is required or desired, the services of an appropriate, competent professional, such as an attorney or accountant, should be sought.
Insurance Markets
Big I Programs
This month’s issue
The October issue is out now!