Neptune Flood Raises Building Coverage Limits and Expands Options
PRODUCT: Neptune Flood Insurance.
COMPANY: Neptune Flood Insurance, a subsidiary of Neptune Insurance Holdings Inc., serves as the managing general agent (MGA). Policies are written on paper provided by eight distinct insurance carriers, with 45 ultimate capacity providers, including reinsurance.
BEST RATING: All carrier partners are rated A- or better.
AVAILABILITY: Available on an open-brokerage basis.
FOCUS: Neptune has increased building coverage limits to $15 million across all primary and excess flood policies while introducing new and enhanced coverages for residential, commercial and residential condominium building association policy (RCBAP) policyholders.
Agent Toolkit: Combat Legal System Abuse
“Property values have continued to rise, but flood insurance coverage hasn’t always kept pace,” said Trevor Burgess, chairman and chief executive officer of Neptune. “By increasing our building coverage limit to $15 million and expanding or adding key coverages, we’re giving agents more ways to protect residential and commercial property owners with the coverage they need.”
COVERAGE DETAILS: Policy highlights now include:
- Building coverage up to $15 million across residential, commercial and RCBAP policies—previously capped at $7 million for residential.
- Business interruption coverage up to $1 million, doubled from $500,000.
- Loss of rental income coverage for apartment properties up to $1 million, doubled from $500,000.
- Outdoor trees, shrubs and plants coverage up to $2,500 for residential properties and $5,000 for commercial and RCBAP properties.
- RCBAP renewal price protection, which lets condominium associations lock in renewal pricing.
Beyond the June enhancements, the products offer coverage options the National Flood Insurance Program (NFIP) doesn’t, and excess flood policies are available to sit over NFIP or other primary coverage.
UNDERWRITING: An agent or consumer enters the property address to instantly assemble the risk profile, drawing on proprietary data. The agent answers a handful of confirming questions, selects coverage amounts and deductibles, and receives a bindable quote in about two minutes. No elevation certificate or inspection is required. Every property is priced individually on its own risk characteristics rather than broad zone-based ratemaking.
Policies are subject to a standard 10-day waiting period before coverage takes effect, shorter than the NFIP’s 30 days, and that waiting period is waived for real estate closings and policy rollovers.
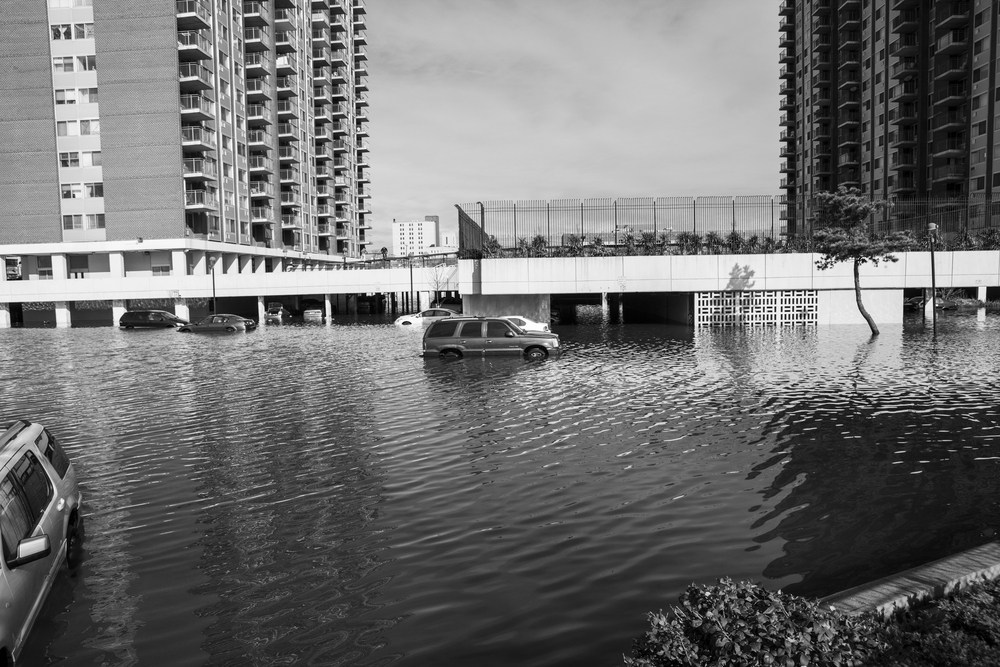
TARGET: Any residential or commercial property owner exposed to flood—which is a far larger group than most people assume, since flooding regularly occurs outside FEMA’s mapped high-risk zones. The $15 million limit specifically opens the door to larger single-building risks that previously required layered placements.
COVERAGE AVAILABILITY: All U.S. states.
CONTACT: Steve Aikens, chief marketing officer, Neptune; 400 6th St S, Suite 2, St. Petersburg, FL 33701.
Will Jones is IA editor-in-chief.
Insurance Markets
This month’s issue
The October issue is out now!